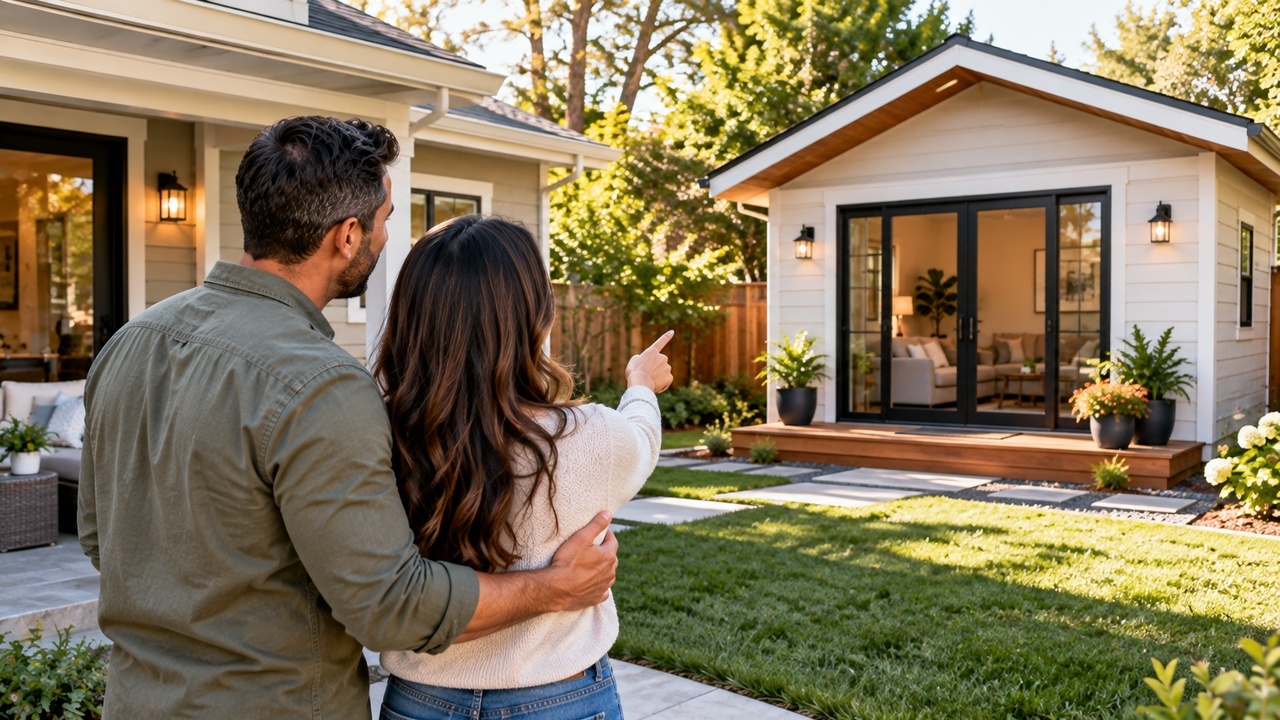
 An accessory dwelling unit can make a property especially appealing. A detached guest house, converted garage, basement apartment, or backyard unit might provide space for relatives, a home office, or potential rental income.
But when you are financing the purchase, that additional living space can introduce questions that would not necessarily exist with a more traditional single-family home.
The Property Has to Be Evaluated Too
Mortgage approval is not based solely on the borrower’s income, credit, assets, and debts. The property securing the mortgage also has to meet applicable requirements.
When an ADU is present, the lender and appraiser may need to understand exactly what it is and how it relates to the primary residence.
Is it a separate structure? Does it have its own kitchen? Was an existing part of the property converted? These details can help determine how the property is evaluated.
Permits and Property Records May Matter
One important question is whether the additional living space was legally created and how it is reflected in available property records.
Buyers should not assume that a finished structure is automatically recognized as permitted living space simply because it looks professionally completed.
If something about the ADU is unclear, additional documentation or investigation may be needed.
Rental Income Is a Separate Question
Buyers sometimes see an ADU and immediately calculate how much rental income it could generate.
That potential income may be useful to your personal budget, but do not automatically assume it can be counted toward mortgage qualification.
Whether rental income from an ADU can be considered, and how much can be used, depends on the mortgage program, documentation, appraisal, occupancy plans, and other requirements.
Ask Before Building Your Budget Around It
If an ADU is an important reason you are considering a property, discuss it with your mortgage professional early. Explain how you intend to use the space and whether you are relying on anticipated rental income as part of your financial plan.
You may also want to ask your real estate professional about permits and available property information. An ADU can be an excellent feature, but it makes the property more than simply a house with an extra room.
Before assuming the additional space will strengthen your mortgage application or generate income immediately, understand how it will be treated in the transaction. That can help you evaluate the property based on what is actually possible rather than what you hope the extra space will provide.